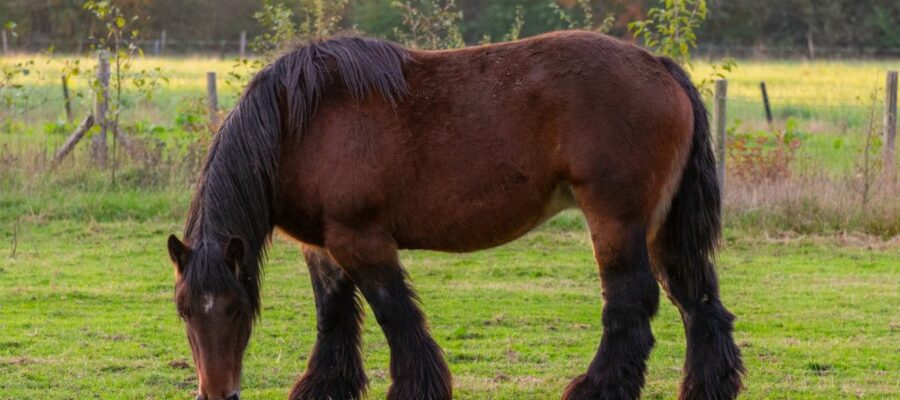
Have you ever had that split-second feeling that your heart has stopped? 🐴 That was exactly what I felt when I found Tornado, my 8-year-old Friesian, lying in his stall and unable to get back up. The vet suspected colic. It was an emergency surgery: €15,000 upfront, with no guarantee he would survive.
That morning, I faced a harsh truth: even with all my passion and savings, I was not ready for that kind of financial shock. My liability insurance? It covered damage Tornado might cause to others, not the medical crisis happening to him.
That is why equine mortality insurance is not a luxury. It is a real safety net. In just a few minutes, you can understand how it helps protect both your horse and your finances.
When passion meets financial reality
It is easy to focus on the bond, the routine, and the joy of spending time with a horse. You stroke the neck, feel the warmth beneath your hands, and listen to the steady rhythm of breathing beside you. But behind that emotional connection is also a significant long-term financial commitment.
The true cost of owning a horse over its lifetime:
| Expense item | Average annual cost | Over 20 years |
|---|---|---|
| Boarding/food | €3,000 | €60,000 |
| Veterinary care | €1,500 | €30,000 |
| Farriery | €800 | €16,000 |
| Total | €5,300 | €106,000 |
And that does not even include the purchase price of the horse itself. Tornado cost me €50,000, but some sport horses can sell for several hundred thousand euros.
The common mistake that can wipe out years of savings
Most owners think the same way I once did: “My horse is young, fit, and healthy. What could possibly happen?” Unfortunately, horses can change from healthy to critical very quickly.
The numbers show how real the risk is:
- 1 horse in 10 suffers from serious colic each year
- Transport accidents affect 3% of transported horses
- Injuries in the paddock account for 40% of veterinary emergencies
Key figure 💡: The average cost of emergency surgery for a horse ranges from €8,000 to €25,000. That is an amount very few owners can produce at short notice.
When an emergency happens, the problem is rarely just the vet bill itself. There may also be transport costs, follow-up treatment, medication, and time-sensitive decisions that need to be made under pressure. In those moments, having a financial cushion matters as much as having the right clinic nearby.
Equine mortality insurance: peace of mind when the unexpected happens
Equine mortality insurance is straightforward: if your horse dies as a result of an accident or illness, you receive the insured value. But not every policy offers the same level of protection, so it is worth looking closely at the details.
The three essential guarantees to check:
All-cause mortality: Covers death regardless of the cause, including illness, accident, or therapeutic euthanasia.
Theft and emergency slaughter: Protects against theft and against emergency decisions made to prevent further suffering.
Additional veterinary expenses: Reimburses part of the medical costs incurred before death, which can be especially helpful in euthanasia cases.
My personal tip ✨: Always ask whether the policy covers euthanasia for economic reasons. It is a painful subject, but if treatment costs rise above 50% of your horse’s value, that clause can prevent an impossible decision.
It is also important to read how the horse’s value is determined. Some insurers base compensation on a declared insured amount, while others require evidence of market value, performance level, age, or health status. Being accurate from the start helps avoid unpleasant disputes later.
How to choose the right coverage without overpaying
Equine mortality insurance usually costs between 3% and 5% of the insured value per year. For a horse insured at €20,000, that means roughly €600 to €1,000 annually.
Practical advice:
- Insure your horse at its real value, neither more nor less, because insurers do check.
- Report any change in health status immediately.
- Choose a deductible that fits your budget; the higher the deductible, the lower the premium.
It is worth taking time to compare policies carefully. A lower premium can look attractive at first, but the cheapest option is not always the most useful one if the exclusions are too broad or the reimbursement terms are too strict. The right policy is the one that fits the horse’s profile, your budget, and the level of risk you are willing to carry yourself.
There can also be differences in what happens after an injury or illness is discovered. Some insurers require prompt veterinary documentation, while others may ask for specific examinations before coverage begins or renews. A quick review of the conditions before signing can save a lot of stress later.
What happened with Tornado? Thanks to the vet’s rapid intervention and a bit of luck, he pulled through. But the €12,000 bill made one thing clear to me: loving your horse also means protecting it financially.
Your next step if you want to sleep better at night
Now that you know the stakes, do not make the same mistake as the many owners who postpone this decision until it is too late. Start by estimating your horse’s real value, taking into account age, level, potential, and health status, then request several quotes.
If you want to protect both your horse and your finances, this is a sensible place to start. Equine mortality insurance will not prevent an accident or illness, but it can make a devastating situation far easier to manage.
Has your horse ever had a veterinary emergency that made you panic about the cost? Sharing that experience can help other owners prepare before they are forced to react in a crisis.
latest posts published
Pregnant Dog: How to Prepare for the Arrival of the Puppies?
Death and Inheritance Rights: Who Inherits Your Pet? What You Need to Know
Senior Dog Kibble: At What Age Should You Switch?

Which Dog Breeds Don’t Shed Hair?

Bringing Your Dog or Cat to the Casino: Is It Really Possible?

What Are the Most Beautiful Cat Breeds?

Why Does My Dog Close Its Eyes When I Pet Its Head?
How to Clean Your Cat’s Ears Without Stress

Sterilizing My Cat: The Real Pros and Cons